Company pension . Performance

Homewardbound11

Registered User
Messages
45
My company pension plan is with mercer moderate growth . Back in 2022 the plan was migrated to a new plan and it is easy to track the performance based on that timeline . The growth on average is a a little over 4 percent . I’m I right in thinking this is below par and is there anything that can be done in terms of improving their performance
I’m conscious moderate growth might not be the highest but it’s a risk5 and given I’m 10 years out I’m cautious of increasing risk.
 
It's not below par if the really dominant assets (80%+) in your fund is bonds/cash and allowing for a modest AMC on the scheme.

If you provide the exact asset split and exact dates you're talking about, and include what charges are on the fund, then maybey someone can give you a meaningful response.

Are you going to buy an ARF or Annuity with the after tax free cash fund?


Gerard

www.execution-only.ie
 
I’m conscious moderate growth might not be the highest but it’s a risk5 and given I’m 10 years out I’m cautious of increasing risk.
 
Sorry for piggybacking here. I've also a mercer company pension with approx 10 years to go to retirement. I'm in a "do it for me" lifestyle approach invested in Aspire moderate growth fund. It's rated a 5 for risk. It seems to have grown 50 percent on what I've put in.

Some colleagues who did not select "do it for me" are in Passive Glob Equity Partial Hedge Fund. Theirs has grown 100 percent. It's a risk 6.

I'm considering moving to that fund, any advices.
 
Last edited:
For those that want to have a stab at answering the latest post.

Info borrowed from Reddit (but it's 2 years old so poster can confirm the current asset splits and AMCs

1. ⁠(Default) Aspire Moderate Growth Portfolio: Active and passive mix; Split: 45% equities, 35% bonds, 13% listed real assets and the rest commodities and alternatives. Aim for fund is 4% return P.A. however it only started in 2021 so there's no historical performance. AMC is 0.23%.

1. ⁠Passive global equity partial hedge: Allocation is 55% passive global equity unhedged, 35% passive global equity hedged and 9.5% passive emerging markets. Globally diversified with 67% North America, 10% Asia, 12% Europe, 5.5% Japan and the rest other. Has approx 1600 holdings with top 5 being apple, microsoft, google, amazon and tesla. Historical returns are 7% P.A. past 5 years and 8.4% P.A. past 8 but it is down the most this year at 17% (compared to 12 for moderate growth portfolio and 14.5 for high growth). AMC 0.08%.
 
Presume when posting annualized returns, the fx is not taking into account as in value of retirement account after them years could be significantly affected by exchange rate particularly this year. Stock market up this year but my retirement account value is down 15% due to weakening dollar.
 
I’m I right in thinking this is below par
What is par?

A lot of people look at their pension performance and compare it to others that are doing better without assessing the risk exposure. The site and others will tell you that equities will provide you with the best opportunity for growth. But with that comes risk. In the 2000's, a 100% equity investor would have seen their portfolio fall by -50% twice in a decade :eek:. Those with bonds in their portfolio would have had some downside protection. The fund they were in probably allowed the fund manager to reduce their equity exposure whereas an equity fund has to remain in equities.
What isn't helping the "managed" fund type investor is the dreadful return of bonds over the last 10 years. Bonds are drag on returns at present rather than a diversifier. That will not always be the way.


Sorry for piggybacking here. I've also a mercer company pension with approx 10 years to go to retirement. I'm in a "do it for me" lifestyle approach invested in Aspire moderate growth fund. It's rated a 5 for risk. It seems to have grown 50 percent on what I've put in.

Some colleagues who did not select "do it for me" are in Passive Glob Equity Partial Hedge Fund. Theirs has grown 100 percent. It's a risk 6.

Again, risk and return. Your colleagues have taken more risk and gotten a higher return. But those gains they have enjoyed are gone and you won't be getting them if you move to equities. In fact, because of the growth of the fund, it is now more expensive for you to join. You need to look at what you are comfortable with and whether your pension fund is giving you the performance you need to have a good retirement. If not, you either need to put more money in and/or take more risk. Putting more money in with have a much bigger influence on how much you get back at retirement than the investment return.
 
Thank you very much for the feedback.

The colleague who were in the higher risk fund actually thought that everyone was in the same fund and I thought everyone was in the one I was in, so I guess we are all pretty bad. Some colleagues got burned by Gars a few years ago, hence most people saying leave it in the standard. However, I thought mine was in a medium risk, but it turns out the moderate risk and high risk Aspire are both graded 5, with the Passive Global one at a six. I would have been happy to do a six instead of a five, but was going on the basis that the company would be putting you into the one with the best return. The objective of the Moderate growth is to achieve Cash Return plus 3.5 - 4.5%.

I looked at the charges and the aspire moderate growth is 0.37 AMC and the Passive Global is 0.22.

The reason I am looking at this now, is that I am almost finished paying the mortgage and can now add some more money to this fund.

The choice of funds are very limited so its either chance the high return or stay in the middle.

Thanks everyone for their feedback. Pensions and investments are a minefield and its great to get some feedback.
 
Hi ,
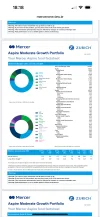
A delayed response , sorry and I don’t know if I have the exact info or time snapshot the Gerard requested . Time wise it was Dec2022 to now . AMC I believe is 0.46 percent ?. Attached is a pic I of the split but I’m not sure if what it was back in 2022 or if it ever changed ? Like the previous poster mine was mercer”do it for me “ option also.

Your questions …..
———————————
If you provide the exact asset split and exact dates you're talking about, and include what charges are on the fund, then maybey someone can give you a meaningful response.

Are you going to buy an ARF or Annuity with the after tax free cash fund?
————————————-
GSheehy . My plan and it’s not exactly thought out now is to go down the ARF route simply to provide something to my kids when the time comes . Over 10 years to retirement . Should I be directing myself in one direction now .?.
 

Attachments

  • IMG_0875.webp
    IMG_0875.webp
    175.5 KB · Views: 26
I've also a mercer company pension with approx 10 years to go to retirement. I'm in a "do it for me" lifestyle approach invested in Aspire moderate growth fund. It's rated a 5 for risk. It seems to have grown 50 percent on what I've put in.

Some colleagues who did not select "do it for me" are in Passive Glob Equity Partial Hedge Fund. Theirs has grown 100 percent. It's a risk 6.

I'm considering moving to that fund, any advices.
For anyone with more than 10 years till retirement, the best (one size fits all) advice is to choose the Passive/Index Global Equity Fund.
But once you are within 10 years, one size fits all advice is not really appropriate.
Your strategy will depend not just on the number of years to retirement but also
  • How old you are and hence how long you will live
  • whether you will ARF vs Annuity, vs Mix
  • whether you want to leave an inheritance or are happy to spend it all
  • whether you are willing to be flexible on your drawdown amount during retirement (in bad years) vs whether you want to get the set amount no matter market conditions
  • The total size of your pot now, vs the amount of money you need to live on
  • Whether your willing to delay retirement if markets are bad
So it's no longer a one size fits all answer.
In 10 years time (even 5-6 years time) the probability is that you will be better off investing in the Passive/Index Global Equity Fund, but it's not guaranteed. So all the above factors become important in your decision.
 
Thanks For the info . We have a annual pension review with our provider but to be honest we just get the same old info that really on contributions and not on what you need to be planning for when you draw down your pension.
 
The growth on average is a a little over 4 percent
Time wise it was Dec2022 to now . AMC I believe is 0.46 percent ?.

The composition of the fund is similar to Prisma 4 from the same provider. The cumulative performance of that fund is circa 29% over the period 30/12/2022 to 26/8/2025 (after AMC and and all other fund charges). You're not going to sort out that anomaly here. You need to make use of the advisor attached to the scheme.

Global Index Tracker (100% equities) is circa 50% on same period.
 
For anyone with more than 10 years till retirement, the best (one size fits all) advice is to choose the Passive/Index Global Equity Fund.
But once you are within 10 years, one size fits all advice is not really appropriate.
Your strategy will depend not just on the number of years to retirement but also
  • How old you are and hence how long you will live
  • whether you will ARF vs Annuity, vs Mix
  • whether you want to leave an inheritance or are happy to spend it all
  • whether you are willing to be flexible on your drawdown amount during retirement (in bad years) vs whether you want to get the set amount no matter market conditions
  • The total size of your pot now, vs the amount of money you need to live on
  • Whether your willing to delay retirement if markets are bad
So it's no longer a one size fits all answer.
In 10 years time (even 5-6 years time) the probability is that you will be better off investing in the Passive/Index Global Equity Fund, but it's not guaranteed. So all the above factors become important in your decision.
I would also add, access to the COAP. If there was two in play that is effectively a €30K a year annuity from age 66.
 
Back
Top