Correct. I said 'If there was two in play....'€15K (52 weeks x €289.30).
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
Company pension . Performance
- Thread starter Homewardbound11
- Start date
I had no idea what that meant.I said 'If there was two in pla
Husband and wife or husband and husband, wife and wife etcI had no idea what that meant.
Secondtimer
Registered User
- Messages
- 12
That fund you posted is the exact same as the one I am in. I think our Management charges are slightly less.Thanks For the info . We have a annual pension review with our provider but to be honest we just get the same old info that really on contributions and not on what you need to be planning for when you draw down your pension.
We only have a choice of a few funds and to be honest, none of them seem particularly brilliant. The one you have posted is the next best result to the Risk 6 one and there is a huge gap between the returns.
The question I am asking, is why are the Aspire funds from Mercer so medicre, if the Prisma similar fund is well out performing?
We dont have an annual review, we get them every few years if even that, but the quality is poor and exactly like you said, they tell us just to pay more in.
Secondtimer
Registered User
- Messages
- 12
For anyone with more than 10 years till retirement, the best (one size fits all) advice is to choose the Passive/Index Global Equity Fund.
But once you are within 10 years, one size fits all advice is not really appropriate.
Your strategy will depend not just on the number of years to retirement but also
So it's no longer a one size fits all answer.
- How old you are and hence how long you will live
- whether you will ARF vs Annuity, vs Mix
- whether you want to leave an inheritance or are happy to spend it all
- whether you are willing to be flexible on your drawdown amount during retirement (in bad years) vs whether you want to get the set amount no matter market conditions
- The total size of your pot now, vs the amount of money you need to live on
- Whether your willing to delay retirement if markets are bad
In 10 years time (even 5-6 years time) the probability is that you will be better off investing in the Passive/Index Global Equity Fund, but it's not guaranteed. So all the above factors become important in your decision.
Thank you very much for this. A lot of food for thought.
I am single with no dependants - not interested in leaving a huge legacy, only 2 neices. I am even considering doing a Spry finance at some point. I As time goes on, Im feeling more like I'd like to get out at 60, even if I did not take the fund till 65.
As our pension provider is very poor in their support (suppose they are not advisors) I should probably consider getting a consultation to look at all the above you have said.
Homewardbound11
Registered User
- Messages
- 45
The composition of the fund is similar to Prisma 4 from the same provider. The cumulative performance of that fund is circa 29% over the period 30/12/2022 to 26/8/2025 (after AMC and and all other fund charges). You're not going to sort out that anomaly here. You need to make use of the advisor attached to the scheme.
Global Index Tracker (100% equities) is circa 50% on same period.
Hi again,
I’m trying to work out 29 percent growth from Zurich and also if I took my calculations wrong . I took my contributions and transfer from dec2022 (a) then took the current value of the fund(b)
(a-b)/a by100 to get a percentage of 15 percent .
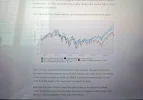
I found chart online of Zurich prisms 4 but it seemed to be performing similar to the mercer one. Have I got something wrong ?.
Attachments
You can only use the transfer amount on that date. The rest of the contributions weren't all invested from that date in 2022. They were incrementally invested since then so they're not going to have all grown by 29%.
Forget the chart as it's for 3 years from June '21.
Forget the chart as it's for 3 years from June '21.
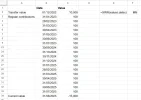
Put the transfer value and all the contributions into a spreadsheet with their dates of payment.Have I got something wrong ?
Then put the current value and today's date at the bottom with a minus sign.
=XIRR(values, dates) will give you the annual rate of return.