Case study Built a free Irish pension calculator — would value feedback from people here

Under the other income sources, would it be possible to have option of inserting an end date for the income source. Also In the PDF report, it would be helpful to have a column for other income in the "year by year" section.
 
Last edited:
@jfrank
It does already. The Irish State Pension is included by default on the retire tab, and you can add a UK one (or any other country's) under "other state pensions" in more options, in £ or €, from the age it starts.
 
Have I got this right?
Conventional pensions: 100% equities assumes 6.5% nominal growth before inflation at 2% and charges
MyFutureFund High: 100% equities assumes 4.5% real growth after inflation and charges

In the pop-up for the actual calculation, it says that MFF Hi used 3.9% p.a. after inflation and charges (assumed at 0.5%). Gemini seems to confirm that you actually used 4.5% p.a.

I believe 4.5% p.a. is the more correct. The Government has stated that charges won't exceed 0.5% p.a. This covers the early years were the fixed charge of 55c per week has a magnified effect. But in the long run the 0.04% p.a. investment cost ensure that MFF will be substantially below 0.5% p.a. fund charges.
 
Last edited:
@Duke of Marmalade
On the SFT: If a pension at retirement would be over that year's threshold (€2.2m now, rising to €2.8m by 2029), the plan shows how much it's over and the 40% tax on the excess, though it doesn't take that tax off the figures.

On growth: fair point on the charges. I'd used the 0.5% cap, but if the long-run cost is more like 0.04% plus 55c a week, the same 6.5% for shares works out at about 4.3% a year real, close to the original 4.5%. Most of the gap was the pension calculator's own 1% default charge. On the 3.9%: that's what the page uses now. I changed it this afternoon, so if you looked earlier you'd have seen 4.5%, and Gemini can't see what the page actually calculates. Have you a link for the 55c and 0.04%? If they're on the MyFutureFund site, I'll use them, which would put high risk at about 4.3%.
 
Have you a link for the 55c and 0.04%? If they're on the MyFutureFund site I'll use them
They are
Note that the admin fee will be adjusted from time to time for CPI inflation. The AMC will depend on the what NAERSA can negotiate with the fund managers. Note that participants seem to be charged the wholesale costs of running MFF and in particular there is no loading for profit or financial advice.
On a separate point nearly everybody will be on the default strategy. This has been set as 100% High risk up to age 50 switching to 100% Medium Risk at age 50 and finally switching to 100% Low Risk at age 60 (crazy but that is what the Act dictates)

MFF participants guide said:
Fees and charges

In MyFutureFund:

An administration fee covers the cost of services provided by NAERSA for running MyFutureFund, and,
An investment management fee covers the cost of the services provided by the Investment Managers.

The administration fee is a flat weekly fee that all participants pay when actively making contributions. The fee has been kept low, currently 55 cent, and has been designed to deliver good value for money to participants, especially when considered over the lifetime of your participation in MyFutureFund. The administration fee is taken from your contributions before they are invested. You will not have to pay the administration fee if you are opted out, have suspended your contributions, or have all employments exempted. This decision was made to avoid a scenario whereby savings pots would be eroded by fees during periods where there were no active contributions.

The investment management fees will be charged as a percentage of the assets under management (AUM). These fees have been kept low and are currently 0.03833%. [/quote}
 
Last edited:
@Duke of Marmalade
Thanks for the link. That's updated now. The calculator uses the actual charges: 0.04% a year plus the 55c a week taken from contributions before they're invested (rising with CPI). On the same 6.5% for shares, high risk now works out at about 4.4% a year real, so your 4.5% was very close.
 
It is an impressive piece of work. It has a lot of moving parts and would need a lot of testing to be idiot proof (idiots can be very expert at uncovering gremlins. :confused: )
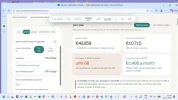
I was experimenting with the investments section in a standalone setting. I thought this would be achieved by zeroising the pension contributions but the below (testing a €10k standalone investment) suggests I am doing something wrong.
1794938193046.webp
 
@Duke of Marmalade
Thanks, and agreed on the gremlins! I think it's the starting figures: the calculator begins with €20,000 already in a pension ("pension pot today", on the "you" tab). Zeroing the contributions stops new money going in, but that €20k still grows to about €42,859 by 65 (today's money), and the lump sum is 25% of it. Set that to 0 as well and you'll see the €10k on its own: the €20,851 is what it grows to. For investments on their own, the investment account calculator (under "more calculators" at the top) is simpler too.
 
Back
Top