Headline from the Business Post (can't access the article as it is behind a paywall), but if residential property is not viable for funds with tax breaks and millions in capital where is the ordinary person with one or a handful of properties going in all this?
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
Why Property Is a Fundamentally Broken Investment In Ireland
- Thread starter stormy
- Start date
"All right, but apart from the sanitation, the medicine, education, wine, public order, irrigation, roads, a fresh water system, and public health, what have the Romans ever done for us?"But outside of a pension scheme, the government does actively work against you building up wealth via ETFs or indeed property.
Yes, the goverment have covered themselves in glory in housing across all the different tenures."All right, but apart from the sanitation, the medicine, education, wine, public order, irrigation, roads, a fresh water system, and public health, what have the Romans ever done for us?"
Agreedresidential property does not make sense.
My comment was not about housing; it was a response to your suggestion that "The government here seems to be actively against people building up personal wealth themselves over their lifetimes to provide for themselves in their old age". The truth is that Ireland has exceptionally generous tax breaks for this.Yes, the goverment have covered themselves in glory in housing across all the different tenures.
Only via pension schemes. The crazy deemed disposal rule on ETFs actively discourages saving and wealth building. If I want to save money for other purposes aside from my pension, it is very difficult to do so. Residential property is now out as well.The truth is that Ireland has exceptionally generous tax breaks for this.
JoeRoberts
Registered User
- Messages
- 1,218
Is that not enough though ? Why should the govt have to forgo tax on profits from investments ?Only via pension schemes.
I'm not asking for tax breaks on any investment you make. I'm just saying don't penalise ETFs via the deemed disposal rule - tax when the person sells as with any other asset and continuing taxing any dividends paid.Is that not enough though ? Why should the govt have to forgo tax on profits from investments ?
I can (and do) earn over 2% annually on cash — even in today's environment. If inflation rises and base rates increase, my interest income will rise accordingly, without being subject to government-imposed caps.
- Cash - no income
Correct there is generally no income from commodities, but its resale value is not limited either. I'm making the point that a property's resale value is capped as its future income stream is capped (unless removed from the rental market). If I produce a ton of barley and the demand goes 100x, I could make a killing. Not the case with investment property - if demand goes gang busters, a tenant needs to be removed for it to be sold to an owner occupier (I'm legally not allowed to increase the rent and not would another landlord, so no upside unless tenant removed).
- Commodities - no income
Bonds are priced at issuance using the matched maturity trading level of rates (which are driven by inflation expectations) plus a credit spread to ensure the expectation is that it has a positive real return. Again there is no cap on the income from a bond - an issuer can freely set the coupon at issuance to whatever the market will allow. Additionally it can also have a floating coupon linked to rates which can freely increase if rates increase, and the government do not interfere here.
- Bonds - fixed income/reducing in real terms
Equities are just partial ownership of companies. What company is mandated to charge below inflation levels on their sales? Of couse the net income to the company itself depends on performance, my point is that it has not been dictated to by government that it must take a real terms cut to income.
- Equities - no fixed income, depends on company performance, can fall on nominal as well as real terms.
I don't know much about Crypto. Is there a cap on what can be earned from it?
- Crypto -
The government has been clear that existing tenancies (pre 1 March 26) will have no reset mechanism. I have little faith that the 6 year reset will actually come to pass for new tenancies. RPZ's came in back in 2016 and we were all told they were to last for three years. 9 years later they seem to have been effectively made permanent showing just how much faith one can have in then. And all this before a more left leaning government comes to power.Market rent has far exceeded inflation over the last 10 years. The proposals seem to allow rents to be set to market level every 6 years. When this is being done it’s likely you will beat inflation.
Would you have data to support the statement. I've tried looking and I see significant growths in salaries over the last 5 years. See table below for example (already pasted in earlier post).That said the majority of salaries have not increased with inflation either.
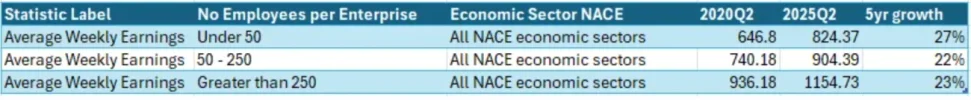
Source: https://data.cso.ie/table/EHQ04
Yes, but only if the property exits the rental market. If they intend to sell after six years, it would qualify as a no-fault eviction, meaning there’d be no rent reset even if such a provision were introduced. In the long run, I don’t see how this alleviates the rental crisis, since the property would ultimately be removed from the rental pool.Small landlords will be able to sell after each 6 year period (or by giving notice now) so the capital appreciation is still relevant.
Thanks for feedbackAny argument is only as good as its weakest point so when you start throwing loads of points at something you can weaken it.
Thanks for flagging. I understand why they think this and it's hard to blame them.Headline from the Business Post
Its also obvious from the trading levels of IRES Reit that investors want out. Its now down 18% since the start of June (i.e. before the reforms were announced).
I think IRES Reit also highlights why the rental market is broken (supporting the arguments in my opening post). Its shares are now trading at a ~30% discount to their net asset value. It seems to be the case for IRES Reit they should liquidate (i.e. sell all their apartments) and close the discount. I suspect if the shares keep tanking (while property prices keep going up) an activist might come in and try to do this. They will only be able to get full value for their apartments/units if it goes to the owner occupier market (as if they get vacant possession by way of a notice of termination, the new landlord would be subject to the capped old rent which I suspect in a lot of cases is well below market, and well below say 2020 levels when adjusted for inflation).
https://finance.yahoo.com/quote/IRES.IR/
Source: I-RES H1 2025 Results
Pg44, Table: EPRA NAV per Share
Basic Net Asset Value per share: 126.9c per share (30Jun25)
Current trading level: 90.0c per share (10am today)
Last edited:
That's because the people who make the rule have pensions but don't have EFTs.If I want to save money for other purposes aside from my pension, it is very difficult to do so.
The people who make the rules have unfunded pensions, so they only need to worry about the tax take required to pay those pensions when they retireThat's because the people who make the rule have pensions but don't have EFTs.
if residential property is not viable for funds with tax breaks and millions in capital where is the ordinary person with one or a handful of properties going in all this?
the article I think answers your question.....international funds have options...this is about as mobile as capital gets...other European residential markets offer Ireland-eque gross yields on resi but without the draconian rent price controls.....some things in business are a two second decision.........Ireland, as destination for residential capital flows, has become a two second decision and that decision is a pass.
For the ordinary person in Ireland of course......your ability to access residential investments in Warsaw, Porto, Lisbon, Milan for example are limited by all sorts of barriers to entry. (proximity, financing, asset mgmt)...Ireland by proximity remains the resi market you have access too......so IMO this is where we're headed the PRS sector will increasingly be a domestic-led investment vehicle.....the issue being the Irish state, Irish pension funds & Irish domestic investment funds lack the scale of capital required to truly deliver the level of housing we require.
So the housing shortage will persist and likely worsen in time - my best guess.....rent reforms have been loosened recently in the hope that it would attract institutional capital, it wont......and so when that failure becomes apparent in increasing monthly rents....rent controls will be tightened again in ways we likely cant imagine today and they'll likely need to trap the existing rental stock as landlords attempt to exit the market.
Last edited:
Investors face asymmetric risk: income is capped, costs are uncapped
The definition of a two second decision for an international fund with options to invest across the globe/Europe.
Last edited:
think IRES Reit also highlights why the rental market is broken (supporting the arguments in my opening post). Its shares are now trading at a ~30% discount to their net asset value.
to which you can add the PLC homebuilders (Glenveagh/Cairn Homes).....we've got the full suite now of "radical" housing reforms from this Government and in the case of the PLC builders the market has yawned (they are flat to down since the summer).....and then in regards to canary in the international PRS capital coalmine IRES.....well the canary is dead.....IRES is worth more in a liquidation than it is as ongoing concern.....its a real time scorecard on the viability of Ireland as PRS investment location.
Which are exactly what you are calling for. Your complaint is, essentially, that the government discourages people building up personal wealth to provide for themselves in their old age, if we disregard the generous tax incentives that the government provides for doing exactly that.Only via pension schemes.
Last edited:
Do you think the ETF itself should pay tax on the dividends that it receives, and the gains that it accrues? Because, right now, it doesn't. The deemed disposal rule is there to prevent indefinite tax-sheltered roll-up of income and gains, and, if you abolish it, you need to introduce some other mechanism to replace it, or you need to make a case for why indefinite tax-sheltered roll-up of income and gains should be permitted.I'm not asking for tax breaks on any investment you make. I'm just saying don't penalise ETFs via the deemed disposal rule - tax when the person sells as with any other asset and continuing taxing any dividends paid.
Other possible mechanisms are
- Tax the ETF on income and gains, retaining deemed disposal only for EFTs which are not subject to taxation in Ireland
- Require the EFT to distribute income and gains each year; unitholders can reinvest if they wish (and of course funds would facilitat this). Retain deemed disposal only for overseas EFTs that do not distribute.
- Tax holders on their proportionate share of the fund's income and gains each year, whether or not distributed. Unitholders can sell or redeem units to meet this liablity if they wish.
- Etc; no doubt we could think of other mechanisms.
The deemed disposal regime is a pain, but it's actually more generous than this, since you can rolled up tax-sheltered income and gains for seven years before paying any tax, which will generally produce a better outcome than paying tax on them each year and reinvesting.
If you think that the Irish tax regime should be more generous again, allowing indefinite rollup, you'll need to make a good policy case for that.
Last edited:
I’ve zero interest in shares. And most certainly don’t want to invest in shares in a REIT. There I’ve no control over anything and if management, (who take generous income), make mistakes then the fund can lose value. Mistakes like over borrowing, leveraging. Property is what I know, and some business (like the hospitality trade) and I’ll stick to that as it makes sense to me. But I’m not starting out now, have learnt from decades of experience and will hopefully sidestep all government pitfalls designed to destroy small landlords.Put 15% of your portfolio on something like this:
I have ETFs (via ishares and vanguard) - not a large amount, but I receive dividends from the ETFs and I pay tax on those dividends.Do you think the ETF itself should pay tax on the dividends that it receives,
The purpose of the ETF is to track a particular index, so it will buy and sell shares to do that ie. the shares in the ETF mirror those in the index by weighting. So the purpose of the buying and selling, is not to make gains but to mirror the index, something quite different. It is not a mechanism to avoid tax but seems to be the thinking at Dept of Finance level.
since you can rolled up tax-sheltered income and gains for seven years before paying any tax
It seems to come down to how ETFs are viewed - a tax avoidance mechanism or simply a way which allows retail investors to invest in shares without having to take the risk on individual shares because it is a mechanism to track an index
We also seem to be a complete outlier with the deemed disposal rule.