I'll be looking for an EO broker soon so could you let me know the broker you used @LittlewillowI would also like to know which broker you used @Littlewillow , could you DM me please.
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
Setting up exec only ARF
- Thread starter NoseyB
- Start date
I wonder are RL giving 0.35% to grab the headlines, but counting on the ARF going to bonds and cash with the higher charge?it is 0.35% - not .25%. 0.40% on bonds/cash. Broker says it gets paid upfront from RL
LDFerguson
Registered User
- Messages
- 5,001
I wonder are RL giving 0.35% to grab the headlines, but counting on the ARF going to bonds and cash with the higher charge?
The 0.35% are index-tracking / passive. The 0.4% are actively-managed. Actively-managed funds would usually be dearer than index-tracking.
NotMyRealName
Registered User
- Messages
- 228
Sorry for the question again Steven, but I'm still muddled by this terminology. Are you say that there's 100% transfer value but that units are then retained for the advisor fee?it is 100% allocation and the advisor fee is being deducted from the fund.
Setforlife
Registered User
- Messages
- 488
LDFerguson
Registered User
- Messages
- 5,001
Sorry for the question again Steven, but I'm still muddled by this terminology. Are you say that there's 100% transfer value but that units are then retained for the advisor fee?
No. Royal London's 0.35% AMC includes their margin. They'll pay the 0.5% commission upfront and then recoup it out of the 0.35% over the first few years. It's not at all unusual for a pension company to not break even on a well-priced product for a few years.
Last edited:
Setforlife
Registered User
- Messages
- 488
And, also, they list newcourt as having 0,25 on lump sum PRSAs. 
NotMyRealName
Registered User
- Messages
- 228
They didn't.Ssssssshhhh.....
Nobody tell @ClubMan that his mate may have gotten paid his fee all along
Classic Irish system - where there is an opportunity to have a really competitive market to the benefit of all pension savers they mess it upOn the subject of PRSAs, it's worth noting that, unlike ARFs, a PRSA provider company has no flexibility to change the charges or offer bespoke special deals because all PRSA variations must be registered with the Pensions Authority
Setforlife
Registered User
- Messages
- 488
A competitive market requires transparency so people can find out what deals are out there, PRSAs having to be registered makes that much more likely that people can access the most competitive deal, rather than the odd one off single deal that no one can know is available. Eg you can look up royal Londons PRSAs on pension authority website and see they offer them from 0.4% charge and ask your broker why they chose to offer you the 1.5% one instead. Admittedly it would be great if everyone named theirs with the fees in the name also. Bespoke special deals are the opposite of being a benefit to all pension savers.Classic Irish system - where there is an opportunity to have a really competitive market to the benefit of all pension savers they mess it up
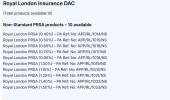
In some cases might it be a lower charge for execution only or low maintenance interactions versus a higher one for full service advisory interactions?Eg you can look up royal Londons PRSAs on pension authority website and see they offer them from 0.4% charge and ask your broker why they chose to offer you the 1.5% one instead.
LDFerguson
Registered User
- Messages
- 5,001
And, also, they list newcourt as having 0,25 on lump sum PRSAs.
We don't work with Newcourt but looking at their PRSA brochure https://nrfm.ie/wp-content/uploads/2026/03/PRSA-Brochure-Trustee-Pensions-Services.pdf (here) I see that 0.25% AMC is for PRSAs of €2 million or more. And it's a self-administered PRSA, so the 0.25% is only for the PRSA structure itself. Unless you keep your €2 million on deposit, pretty much any other investment choice will have its own additional charge on top of the 0.25%.
Setforlife
Registered User
- Messages
- 488
Check, although I like the idea of the pension check site, it’s a bit opaque that all you can do is look at charges and then fill in a form which I guess they send to brokers who may not even offer (or can’t offer) the prsa you are interested in. Although I guess you could use their information to contact the companies themselves.We don't work with Newcourt but looking at their PRSA brochure https://nrfm.ie/wp-content/uploads/2026/03/PRSA-Brochure-Trustee-Pensions-Services.pdf (here) I see that 0.25% AMC is for PRSAs of €2 million or more. And it's a self-administered PRSA, so the 0.25% is only for the PRSA structure itself. Unless you keep your €2 million on deposit, pretty much any other investment choice will have its own additional charge on top of the 0.25%.
Still every bit of new information is interesting. I certainly wasn’t aware Irish Life has a 0.25%/0.3% fee prsa. As someone who intends moving a largish DC pension with very low charges to a PRSA or 2 in 5-7 years any extra information is good information.
LDFerguson
Registered User
- Messages
- 5,001
Check, although I like the idea of the pension check site, it’s a bit opaque that all you can do is look at charges and then fill in a form which I guess they send to brokers who may not even offer (or can’t offer) the prsa you are interested in.
I find it a bit odd. You find the lowest-charge PRSA on this website and then they pass you to a broker. So the broker is getting a lead of someone who wants the lowest-charge PRSA available. They might or might not need advice. But if they're looking for the lowest-charge PRSA, that means it's the version that pays lowest (or no) commission. And the broker also presumably has to pay the pension check site for the lead. As a broker, it's not something I'd be jumping at.
Setforlife
Registered User
- Messages
- 488
Yeah, not sure the model works, I’d assume there would be no point approaching a broker via the site.then again it doesn’t have to work too well. They are just using the pension authority published data and showing it in a clear way, which the pension authority should already do really rather than hiding it away in a spreadsheet.find it a bit odd. You find the lowest-charge PRSA on this website and then they pass you to a broker. So the broker is getting a lead of someone who wants the lowest-charge PRSA available. They might or might not need advice. But if they're looking for the lowest-charge PRSA, that means it's the version that pays lowest (or no) commission. And the broker also presumably has to pay the pension check site for the lead. As a broker, it's not something I'd be jumping at.
Although I would say isn’t absolutely everyone looking for the lowest charge PRSA? It’s finding one and then being able to access it that’s the hard thing!
The real difference here is that the consumer knows the charges in advance. A search for that horizon fund shows it only mentioned online as a recommendation (via pension check) on ask about money in 2025. It’s in the June pension authority list with a 0.5% charge listed and 0.25 discount so it appears real. Doesn’t seem to be findable anywhere on Irish life site, all their prsa docs link to a 4.5% charge ‘Clear’ one.
Possibly its broker only so can never actually be accessed for 0.25%
No. Some people don't shop around. Some people don't want execution only but will pay more for an advisory service. Etc.Although I would say isn’t absolutely everyone looking for the lowest charge PRSA?