What’s the minimum number of EU contributions that can be used to qualify for state pension contributory?

Dr Strangelove

Registered User
Messages
2,767
I worked a summer in Germany about 25 years ago.

I vaguely remember getting a German social insurance number but have lost all payslips and I didn’t have a contract.

Is it worth trying to get a record (if any) of German social insurance paid?

I may be a few short of 2080 by 66th birthday.
 
You can find your German social insurance number very easy by contacting DRV in Hamburg. They should be able to locate your data just by using your name and birth date.

Any EU contributions won't increase your Irish pension. You cannot just add a few foreign contributions to reach the 2080 level.
Using EU contributions for the Irish contributory pension makes only sense to fulfill the 520 contribution rule to get something at all- or activate any Irish credits. In all other cases you are better off to apply for separate pensions from each country.

Minimum EU contributions used to get across the 520 contribution line depends on the country you want to use. The Germans have a system of monthly contributions. Which needs to be changed into the Irish weekly system when it comes to the calculation. If you worked one day in Germany, your contribution counts as a full month. Similar in Ireland- a minimum earnings of 38 euros secure you a full week count. The problem is when the Irish side changes the German month into Irish weeks. DRV will deliver a list of all German contributions when it comes to calculate your pro rata pension. Unfortunately they show the exact dates when you worked. Let's say you worked from the 15th of a month to the 31st of the month. For the Germans this counts as a full months contribution. You might think the Irish side just changes this into 4 weeks of contributions under the Irish system. Not so- they see the exact dates...15th to the 31st- which is only 2 weeks in Ireland. So a full German contribution could suddenly lose half of its value when it is exchanged under Irish regulations.
To answer your question in the title of the thread: You can use the lowest amount of foreign contributions needed to bring you over the 520 line.
But beware of the small print!
 
Any EU contributions won't increase your Irish pension. You cannot just add a few foreign contributions to reach the 2080 level.
Using EU contributions for the Irish contributory pension makes only sense to fulfill the 520 contribution rule to get something at all- or activate any Irish credits. In all other cases you are better off to apply for separate pensions from each country.
I’m a bit confused!

I worked from memory about 7 weeks ever in Germany.

What possibly could this get me in Ireland if anything at all?

I have about 700 PRSI contributions to date and should be about 2050 on 66th birthday.
 
I’m a bit confused!

I worked from memory about 7 weeks ever in Germany.

What possibly could this get me in Ireland if anything at all?

I have about 700 PRSI contributions to date and should be about 2050 on 66th birthday.
Those contributions in Germany won't bring you anything in Ireland. They only would have helped you to bring you over the 520 contribution line. But since you are already over that line you have no need for any of those German contributions at all anymore.
Applying for a German pro rata pension in the future makes no sense either-you would need a full year's German contribution first.
As far as I know you can ask for a refund of your German contributions from Germany when you reach pension age. But since you have only 7 weeks clocked up it should be only very little and not worth the effort.
 
I have about 700 PRSI contributions to date and should be about 2050 on 66th birthday.
Under current rules you could defer your pension beyond age 66 to get your extra 30 contributions. These could come from voluntary or ARF drawdowns.

You could claim pay related jobseekers allowance while waiting for your contributory pension.

After reaching the 2080 level you get full pension plus a small amount extra because of the deferral.

You would reach breakeven point quickly as your losses are only the difference between the 2050 level pension and the jobseekers benefit.
 
Last edited:
You would reach breakeven point quickly as your losses are only the difference between the 2050 level pension and the jobseekers benefit.

Thank you. Although I may well do some employment or self-employment that year. I'll work things out closer to the time and TBH I expect rules will have changed a bit by then anyway.

I may seek out my German insurance record out of curiosity but it seems it cannot be of any use.
 
Under current rules you could defer your pension beyond age 66 to get your extra 30 contributions. These could come from voluntary or ARF drawdowns.

Presumably one would have to defer applying for the pension for a full year?

Or does the system allow someone to claim a contributory pension when one is aged say 66½?
 
From citizens advice.
This implies that any deferred date can be chosen.
You don't have to defer for full year periods.

"The State Pension (Contributory) is paid to people from the age of 66 who have enough (PRSI) contributions. From January 2024, you can choose to start claiming your State Pension (Contributory) anytime between the ages of 66 and 70.

Choosing a later start date is called deferring your pension. You can defer your start date up until you turn 70."


From gov.ie

"You can choose a date between age 66 and 70 to access any State Pension (Contributory) entitlement you may have."
 
Last edited:
From citizens advice.
This implies that any deferred date can be chosen.
You don't have to defer for full year periods.

"The State Pension (Contributory) is paid to people from the age of 66 who have enough (PRSI) contributions. From January 2024, you can choose to start claiming your State Pension (Contributory) anytime between the ages of 66 and 70.

Choosing a later start date is called deferring your pension. You can defer your start date up until you turn 70."
From gov.ie
"You can choose a date between age 66 and 70 to access any State Pension (Contributory) entitlement you may have."

Good spot! I double checked it with the relevant Operational Guideline which states as follows:
Pension Age
From 01/01/2024 a person reaching age 66 can defer access to their pension to a date at any point between age 66 and age 70. They will not be backdated to their 66th birthday when they chose a date to access their pension. This is the date entitlement/payment starts.

I also looked at the pension application form which asks:

12. Do you want to claim your pension on your 66th birthday? Yes / No
If no, what date between the age of 66 and 70 would you like to claim your pension from? DD MMM YYYY
 
Last edited:
OP here.

I actually found my Rentenversicherungsnummer (basically a German PPSN) from the early 2000s. Then I wrote a letter to Deutsche Rentenversicherung looking for a record of any contributions I made in Germany.

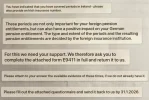
They wrote back to me - at my Irish address - and the letter is very strange. It doesn't provide me any record of my German contributions, but instead seeks a record of my Irish contributions. Translation of the letter below. There is a long annex listing employment, self-employment, home caring, etc.

What should I do? All I want is a record of my German contributions, if they even exist. I will almost certainly never live and work in Germany ever again.

1765131414898.webp
 
I was able to order the record of my German contributions directly online (link) and got a response within a few days. It must come by post but it seems they have your correct Irish address already. What you want is "Versicherungsverlauf".
1765230746156.webp
 
@ Dr Strangelove:
DRV wants to do what is called a "Kontenklaerung".
In post #3 you tell us that you only worked for 7 weeks in Germany. That is very little. You may might have made no contributions at all when you worked there. If you worked as a student, you made no social contributions because you worked for less than 3 months in that year. In this case you do not have any record of contributions because your employer did not have to make them- both you and your employer were exempt from making social insurance contributions. You had to pay no tax either. You will have only a social security number because your employer was legally required to enrol you in the system.
The reason why DRV is looking for your Irish details is set in the EU social security laws. Your Irish recorded social insurance times may count for a possible future German pension if you ever clock up more than 12 months of paid contributions before you reach German pension age- 67 for you- and probably rising to 68 until you reach pension age.
 
Last edited:
You may might have made no contributions at all when you worked there. If you worked as a student, you made no social contributions because you worked for less than 3 months in that year. In this case you do not have any record of contributions because your employer did not have to make them- both you and your employer were exempt from making social insurance contributions.
I was a student in Ireland but not in Germany. Does that make a difference?

I worked for a proper company but was paid cash weekly. After I left the job there was some palaver where they made me come back in to head office to sign on a piece of official-looking paper with my Versicherubgsnummer on it.
 
You was classified as a student so. It did not matter that you studied in Ireland. This means there were no contributions paid by you or your employer. The paper you had to sign probably stated that you are a student and you had to confirm that with your signature. Your employer needed that for the tax and social insurance people to confirm that he was not obliged to take any contributions from your wages.
You are flogging a dead horse...
 
I doubt that your employer has any records of something from the year 2000. Why should the company do so. You was a student, you did not have to make any compulsory contributions. And neither had your employer. That is why DRV did not present you with any contribution record. They cannot show what does not exist. The only thing what does exist is your German PPS (Versicherungsnummer) number. But without any recordings of any social insurance contributions. You never made any.

Here is one link to the situation:

https://www.deutsche-rentenversiche...023/230823-studieren-jobben-rv-beitraege.html

Quote:

"Versicherungsfrei bleiben Studentinnen und Studenten, wenn das Arbeitsverhältnis auf maximal drei Monate oder 70 Arbeitstage pro Kalenderjahr befristet ist. Auch während eines Pflichtpraktikums entfallen die Beiträge. Arbeitszeit und Verdienst spielen in beiden Fällen keine Rolle."
 
Last edited:
hi
rather than opening a new thread would anybody have experience of claiming for three years worked in the USA, do these count towards reaching the 2080 and will it qualify me for a tiny pension from the US
Thanks in advance for any replies
 
Back
Top