Key Post PRSI and planning retirement

52 Class S PRSI Contributions disregarded as I worked for one day as movie extra – Class A

I have been a stay at home mother and my only income is some dividend income >€5,000, from which PRSI is deducted at 4% Class S and this PRSI contribution qualifies me for the Contributory State Pension. However in 2023, I worked one long day as a movie extra in Cork and earned about €152 from which PRSI was deducted but as Class A.​

Recently I noticed that my 52 weeks Class S contributions have been disregarded for 2023 and when I rang the Department of Social Welfare, I was told that because I have a Class A contribution that my Class S contribution were disregarded for pension entitlement purposes as the Class A income was considered my main income, however this leaves me with only 1 week rather than 52 weeks contributions for 2023.

The only suggestion that I was given was that I could make a voluntary PRSI contribution of €500. This seems very unfair.

In addition with my children now grown up and wanted to get back into some part-time work but unless I work 52 weeks a year, this rule would prevent me from working casually.

Any advice?
 
@Revington

You could try signing on for class A Jobseekers credits.

You can be in both the class S and class A systems at the same time.

Then if you take up employment, you can restart your Jobseekers credits after each period of employment ends.

This will ensure that you get 52 reckonable contributions each year. (a mix of paid and Jobseekers credits)

You are allowed a maximum of 1040 credits.
You are probably entitled to carers credits.
Only up to 520 of your maximum credits can be Jobseekers credits, so you need to be mindful that you could run out of useful Jobseekers credits.

Another method of preventing your Class S contributions from converting to non Reckonable contributions is to have some earned self employment each year.

This could be any small amount.

For instance you could do a small job for a friend or family member in return for payment. Then submit this as earned self employment in your tax return.
 
Thanks Class S for that useful info.

For 2024, my PRSI record is only showing 2 Class J contributions which were 2 days helping out with the elections. Now i haven't filed my 2024 tax return yet, but i am a bit nervous of my unearned income Class S contributions being converted to Class K. Would you know if Class J contributions convert Class S contributions to Class K, in the way a Class A contribution would?
 
The wording on the Prsi rules is that if unearned income (dividends) are your only income source and are 5k or more you will get 52 class S contributions.

If you have another source of earned income your unearned income gets you 52 class K contributions. These are not Reckonable.

However if you also have another source of earned self employment income your unearned income will remain at class S.

I know for certain, as indeed you do as well, that any class A earnings convert the unearned income to class K.

I also know for certain that any class M income will also convert the unearned income to class K. Class M is not reckonable.

Class M is applied to pension income. There is zero charge to the pensioner for class M.

Class J applies to earnings below 38 euro per week. There is zero charge to the worker for class J. Class J is also not Reckonable.

Were you paid for the election work ?
If it was voluntary you should be okay.

What does all this mean to you ?

I can't be certain, but class J is somewhat similar to class M.
You also have a small amount of earnings in addition to your unearned income. This might be enough to cause the conversion to class K.

You could contact DSP and ask them if the class J will convert your unearned income to class K.

If they say that you will get class K, you could do as I suggested in the message.
 
Last edited:
I also know for certain that any class M income will also convert the unearned income to class K. Class M is not reckonable

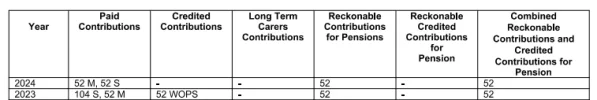
For the last 2 years i have 52 class M's from an occupational pension
I also have 52 class S's from an ARF, (the 104 S in 2023 is a mistake!)
1752699649193.png
When i get to state pension age, will these S's be converted to K's? (before this i have 40 years of class D's)
 
When i get to state pension age, will these S's be converted to K's
No, you are okay.

The 52 class S from an ARF are treated the same as if they were from earned self employment. They will never be converted to class K.

The 104 for 2023 is not necessarily a mistake.
If you had any other source of unearned income, no matter how small, this will generate another 52 class S.

For instance if you had a small amount of bank deposit interest.

People with earned self employment, an ARF and bank deposit interest would get 156 class S per year.

This whole area of Prsi rules is a nightmare to understand.

A person with unearned income from bank deposit interest, rental and dividends will have all their Prsi from these converted to class K if they also have class M.

If this person also has an ARF their Prsi will remain at class S.
 
@S class you are a mine of information. So I have an ARF (class S) and also did the elections last year (class J). So far so good.

To get the 40years/2080 prsi weeks, I need to keep getting the ARF/ S stamps until I’m 62. However I’m considering taking a DB early from age 60 (class M?). Would that stop my S stamps from accumulating or have any other impact I haven’t thought of?
 
@ginslia
When you take your DB pension the class M will not interfere with the class S from your ARF.

You can have any other class of Prsi alongside the ARF class S.
You could get some class A employment or more class J election work if you wish.

This includes Jobseekers credits. You could claim Pay Related Jobseekers Benefit when you retire and remain signing on for Jobseekers credits. This could assist you to claim BP65 if you got some class A employment before age 65.
 
My birthday is in late Jan. In the year of my 66th birthday would it be possible to be credited with 52 Class S contributions if 5k is withdrawn from an ARF before reaching 66?
 
My best guess on this is that even if you get 52 class S on your Prsi record, only the Prsi associated with the weeks up to your 66th birthday will be reckonable for the COAP.

The reason I say this is that pre 95 public sector workers who pay class B or class D, and who have a 5k ARF drawdown in the year they cease public sector employment will have 52 class S on their Prsi record, but class S is only reckonable for the weeks beyond their class B or class D contributions have ended.

For example of they had 22 class D, they would only have 30 class S Reckonable.

Class S is always 52 on your Prsi record but some of these might not be counted as Reckonable.

If you have monthly drawdowns Prsi class M will apply for the calendar month of your birthday.

If you took a lump sum drawdown on a date before your birthday you might get a few contributions for the weeks before your birthday, but if class S applies you will pay Prsi on the lump sum drawdown.

So for a 5k drawdown you would pay over €200 Prsi.

You should contact DSP to get a definite answer to your question.
 
I have been working and getting a class A credit every week since second week of January in 2025.
I also have rental income and an occupational pension. Will my class A contributions be affected by my rental income or occupational pension?
Thanking you in advance
 
Do you have an ARF ?

Without an ARF your rental income will be class K because you also have an occupational pension.

Your class A contributions will not be affected by your other incomes.
 
Thanking you ClassS.I don’t have an ARF, so I am depending on my 2025 contributions to reach more than 520 fully paid contributions.
 
For the over 65 Payment the following is stated under the eligibility criteria;

'Have paid at least 39 PRSI contributions at Class A or H or have credited contributions in the governing contribution year. At least 13 of these contributions must be paid from employment in the governing contribution year, the two years before this, the last year or the current tax year'

Does this mean the 13 need to be in the same year or can you combine 2 or more years from the above. i.e. 6 contributions from the year you turn 61 and 7 from the next year?

I wasn't sure from the way it is written. Thank you to anyone who can clarify
 
On ARF's 500 PRSI is levied on 5k ARF income? Why not 4.2% I see there is a minimum of 650 has it gone up? All seems a bit odd, less than 5,000 and no PRSI but you could pay voluntary contributions. Would this be better value if trying to get to 2080

Unfortunatley a lot of this is hard to forecast and people may need to make decisions 5-10 years out

 
Back
Top