Post 1995 Local Government Pension & State Widows Contributory Pension & Supplementary pension at retirement

etaylor

New Member
Messages
5
Having been unable to find any information online to this query maybe somone can help shed light.

Summary
Worked for 20 years in the private sector.
Worked in Local Authority (LA) 18 years - many years part time - Pension is co-ordinated with the State Pension - paying Class A PRSI Contributions.
Due to retire from (LA) at aged 65 in early 2026.
I have full PRSI contributions to date for a full State Pension - 2300 PRSI contributions to date.
Presently in receipt of a Widows Contributory Pension based on spouse PRSI contributions who worked paying Class A PRSI contributions for 44 years .

My question relates to my entitlement to Widows Contributory Pension when and after I retire.

I believe a Public Servant pre-1995 who paid Class D PRSI contributions is entitled to receive a Widow Contributory Pension together with their full Public Service Pension from their employer.

My LA Pension is co-ordinated with the State pension and from what I read online you are entitled to only one Social Welfare payment.

Am I entitled to receive a Supplementary Pension in respect of the Widows Contributory Pension to bring my pension equivilent to a person who paid Class D PRSI assuming we have the same service record.

Therefore what can I expect to receive at retirement ?

Would this be correct?

Age 65 up to age 66 - LA Pension portion direct from employer + a Supplementary Pension totalling the full amount of the State Pension plus full amount of the Widows Contributory Pension
Age 66 and there after - LA Pension portion direct from employer plus a Full State Pension plus a Supplementary Pension which would equal Widows Contributory Pension.

Thank you .
 
Am I entitled to receive a Supplementary Pension in respect of the Widows Contributory Pension to bring my pension equivilent to a person who paid Class D PRSI assuming we have the same service record
I am not familiar with this exact situation but I am fairly sure you are not entitled to a Supplementary Pension in these circumstances.

An example might illustrate.
Mary has worked in the public service part-time for 18 years, accumulating 12 years of pensionable service. She has also worked in the private sector and has over 2080 full rate Class A contributions. Mary's is in receipt of a widow's contributory pension based on her husband's PRSI record.
Mary will retire at 65 on a pensionable salary of €70,000. Just say the State Pension at retirement date is €16,000.

Mary's Occupational Pension can be approximately estimated as:

(70,000 * 12/80) - (16,000 *12/40) = 10,500 - 4,800 = €5,700.

Mary receives this Occupational Pension in addition to whatever benefits her PRSI records entitle her in accordance with current DSP rules. At 66 Mary will be entitled to a State Pension of €16,000 pa in addition to her Occ Pension so there is no Supplementary Pension.
Under current DSP rules Mary cannot receive both a widow's pension and a state pension - she gets whichever one is most favourable to her.
I am not sure of Mary's situation between 65 and 66 but I assume she will get either the Widow's Pension or the Over 65 Payment but not both. On the other hand if Mary stayed in employment for this year she could continue to receive the Widow's Pension along with her salary. It does seem like an anomaly but those are the rules.
 
Thank you for your reply,

This seems unfair if I am correct that a pre-1995 Public Servant receives their full Pension together with Widow Contributory Pension when retired.

Thank you for the information.
 
This seems unfair if I am correct that a pre-1995 Public Servant receives their full Pension together with Widow Contributory Pension when retired.

Its a DSP rule rather than a public service pension rule. They will not allow the State Pension and the Widows/Widowers pension to be paid simultaneously - even at a partial rate. If they altered these regulations (unlikely) then you, and lots others, would benefit.
 
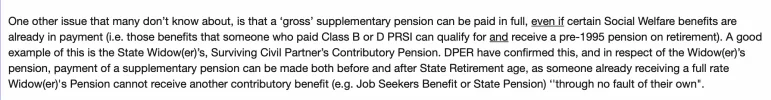
Saw this thread from @Pont62, it would appear if you are already in receipt of a widows/(er's) pension/now called Bereaved Partners Pension (sorry for your loss), this is not deemed as one of the supplementary relevant benefits, so technically, you cannot obtain the SCOAP, as you are currently in receipt of a DEASP benefit, and as this is indeed out of your control, you are due this OSP from your PPA, along with your occupational pension. Now I may be interpreting this all wrong, but worth checking it out. Good luck.
Screenshot 2025-08-03 at 17.52.59.png
 
Last edited:
@etaylor, this may interest you also. It would appear you can remain on widows/(er's) pension, even when you reach the age of 66, you do not automatically have to go onto the SCP, there is no requirement to do so.
The potential benefits associated with both pensions, appear to be like with like, i.e living alone allowance, home benefits package and fuel allowance (means tested), but you need to check this out further, just in case something is in one and not the other.
This is not part of the Relevant Benefits referred to in relation to the OSP/Supplementary Pension.
 
Last edited:
Just a follow up to @Fionclaire's message referring to my post of May 2024 regarding entitlement to a supplementary pension while also in receipt of one of a small number of contributory social welfare benefits where entitlement can be based on PRSI Class A, B and D contributions (unlike the majority of benefits that are based on Class A contributions only).
@Ruffian is correct, DSP will not pay two contributory benefits at the same time, even at partial rates e.g. State Pension Contributory (SPC) and Bereaved Partner’s Contributory Pension (BPCP).
Where an individual under age 66 is receiving the maximum Bereaved Partner’s Contributory Pension (BPCP), currently €249.50 pw for someone under 66, on reaching age 66 DSP will simply increase payment to the over 66 rate of €289.30pw (same rate as the max State Pension). There is no compulsion to claim the State Pension at 66.
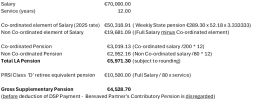
Since DPER have confirmed that the BPCP is not taken into account (before or after age 66) when calculating a supplementary pension, a local authority superannuation pension based on @Ruffian's example would be:

1760089037196.webp
 
Thank uou for your comments .

Have you received confirmation from your Pension administration that you will receive Occupational Supplementary Pension (OSP) whilst in receipt of BPCP both from 65 years and from age 66 years indefinitely (once you comply with BPCP rules )?.

I have been advised by my pension administration that they do not give OSP figures or entitlements until after retirement. How can it be that a Pensions Admindtaion cannot give you a definite answer to entitlements. How can you decide when to retire if you do not have all the facts & figures. Where do I go next to get answers ? Has anyone else been in a similiar situation ? At this point I am very frustrated with no answers . It would never happen with a private pension. The rules are the rules - I just want to know my entitlements I want to know one way or another that BPCP will be disregarded despite the fact I am entitled both the BPCP and the State Contributory Pension but for the fact that I cannot claim more than one Social Welfare payment." through no fault of my own" Am I interpreting Circular 24/2024 correctly?

Has anyone else been in this particular situation and did you receive OSP.

I want to retire in January and need to give notice - this is all dependant on getting answers.

Thank you all .
 
Hi @etaylor,

My public service employer obtained confirmation on this matter from DPER before I retired.

The purpose of a supplementary pension is to ensure that the combined value of a post 1995 retiree's (Class A PRSI) occupational pension and their entitlement to certain State Benefits (e.g. State Pension Contributory, Jobseekers Benefit, Illness/Invalidity Benefit), is not less than the occupational pension they would have received if calculated on a non co-ordinated basis (e.g. 50% of final salary for 40 years service as a Pre 1995 retiree).

However, as Class B and D PRSI contributions also count towards the BPCP, a pre 1995 retiree who is also a widow/widower/ bereaved partner can receive the BPCP in addition to their non co-ordinated pension. A post 1995 retiree would therefore be at a significant financial disadvantage, compared to a pre 1995 colleague, if the BPCP was taken into account when calculating a supplementary pension. BPCP (previously known as the Widow/Widowers Contributory Pension) is not defined in any of the public/civil service superannuation scheme legislation as one of the State Benefits to be taken into account when calculating a supplementary pension.

As previously mentioned, if you are already in receipt of a full BPCP (under 66 rate), on reaching age 66 DSP will simply increase the amount you receive to the over 66 rate and, due to DSP's rules preventing payment of 'double' contributory benefits/pensions, you are not entitled through no fault of your own, to either a 'Benefit Payment for 65 Year Olds' or the 'State Pension Contributory'.
 
I refer to my earlier posts about receiving a public service supplementary pension while also receiving the Bereaved Partners Contributory Pension (BPCP), that is not defined as a Relevant Benefit in Circular 12/2024. Unfortunately, the information I obtained on this was only partially correct.

I now understand that a supplementary pension is still payable to a pensioner while under age 66 where they are not in full time employment, or self employed, and have not claimed a Relevant Benefit from DSP (or where the Relevant Benefit has expired e.g. Job Seekers Benefit).

At age 66, a pensioner must apply for a State Pension Contributory if they want to claim a supplementary pension, even though DSP will allow them to continue receiving the BPCP if it's value is equal to, or greater than their State Pension entitlement. When calculating a supplementary pension, the value of their State Pension entitlement, even if not being received due to staying on the BPCP, will be included in the calculation of the supplementary pension. If someone has entitlement to maximum rate of the State Pension they will not qualify for a supplementary pension.

Although, Circular 12/2024 provides far better guidance than was available before, there are still some issues that are not covered (like this). I can't guarantee that the information I have is correct, so if anyone has had a different experience of claiming a supplementary pension in these circumstances please post.
 
Following my post of 21st January, I have pursued this issue further with my pension provider who has now obtained clarification on this matter from DPER, who have confirmed that the Bereaved Partners Contributory Pension (BPCP) is not a relevant benefit under Circ 12/2024 and is not therefore taken into consideration when calculating a supplementary pension. In addition, at age 66 there is no requirement for someone already receiving the BPCP to claim the State Pension Contributory. Such a requirement will only apply if they re-marry or co-habit.
As a result, someone receiving the BPCP can still claim a supplementary pension regardless of being under or over 66.
 
@Pont62
FYI - I retired at age 65 years and am receiving BPCP + LA pension supplementary pension. I have to apply next year at age 66 years and have been told verbally by pension provider that if on BPCP I will continue to receive a supplementary pension - that BPCP is not a relevant payment - happy to hear you received the same information in the end.
 
In relation to the occupational SP is it still the case that notional service is not included when calculating entitlement to Occupational SP
 
In relation to the occupational SP is it still the case that notional service is not included when calculating entitlement to Occupational SP
This is a concern for me as I am buying back 11 yrs. I have approx. 8 yrs of paying PRSI in the private sector before I went into teaching. I put a number of questions about this into copilot. Copilot said that these 8 yrs will make up a lot of the shortfall that I will have with the 11 yrs of NSP. It states that it doesn't matter where or when you made PRSI contributions - that all your contributions are considered over your working life when calculating the OSP.
Anyone else able to throw some light into this? I recall a recent commentator on here saying that my 8 years of paying PRSI won't make much difference to my OSP.
Thanks
 
Copilot said that these 8 yrs will make up a lot of the shortfall that I will have with the 11 yrs of NSP. I
Well, unless there have been recent changes, I think Copilot is mistaken. Circular 12/2024 is quite clear:

"Accordingly, as no additional notional service has been purchased in respect of an OSP, purchased service is excluded when calculating any OSP."

Your 8 years counts towards the State Pension, of course.
 
Back
Top