Moneymakeover Planning for retirement

Ballymag

Registered User
Messages
42
Age 53
Spouse age 55

Children aged 19 and 16

My income €92,000 a year – civil servant
Spouse income €92,000 a year – civil servant

Home value: €550,000
Mortgage : €95,000

Interest rate: Tracker mortgage - think its .5 or.75 percent above ECB rate
Not finished until 2035 - 30 years
No other loans or credit. Generally saving every month.

Savings:
Bank: 40k
Credit Union: 36k

Pension:
Both of us have pre 1995 civil service pensions:
Spouse: About 6 years left until 40 year maximum
Me: Currently have 30 years due to some years working part time.
I took out an AVC with Cornmarket 3.5 years ago: Value at age 60 would be between 70-73k. 15k can be taken as a lump sum. Think fees are about 550 per month which I could increase. Looked at the Notional Purchase Scheme where I can buy back service but it seemed very expensive.

Educational fund for kids: They have been gifted 3k per year from my mother (to minimise inheritance tax later) so there is enough for college fees.

Inheritance:

As an only child I am due to inherit a house. Currently in Fair deal scheme and will owe back about 80k on the home loan portion. House now worth 400k plus. Also cash assets of approx 30k - rented out so this balance is increasing every month.


Questions

How best to maximise the cash that we have?
I would like to pay down the mortgage but had been keeping it to pay the fair deal 80k bill when it happens. I'd like to keep the house after I inherit it and rent it out. Its currently rented under the Accommodation Recognition Payment Scheme for Ukrainians. If I use the spare cash to pay most of my mortgage, could I get a small mortgage on the house to pay the 80k - then pay it off with rental income?
Am also concerned about inheritance tax if the house value continues to rise.

Pension: Would be interested in finding out if I could retire earlier than 60 - my health has not been great in the last year and not sure I want to do another 6.5 years. Should I pump more into my AVC - if I am paying less mortgage I could definitely increase contributions etc.

Any advice welcome!
 
Check out these threads for information on pre 95 early retirement.


I took out an AVC with Cornmarket 3.5 years ago: Value at age 60 would be between 70-73k. 15k can be taken as a lump sum. Think fees are about 550 per month which I could increase.
Do you actually mean "fees" here? :eek:
Or do you mean "contributions"?
 
Apologies - I mean contribution of 550 per month - I don't know if this means I am already maximising my tax incentives - would it still be worth pursuing?

On the house rental - I would hope that my current Ukranian tenants would stay - they have been with me since the war broke out and are really good tenants. However they are paying 1200 per month + 400 per month contribution under the ARP scheme which is due to finish in Feb 2026. This is well below current rental rates so will need to decide what to do - whether to get tenants able to pay the full rate but who know who I would get or stick with existing tenants paying a lower rent.
 
Any advice welcome!
Well questions first.

How much are you both earning after tax.
Where is that money going.
Mortgage monthly?
Savings monthly?
Confirm you need zero for college? (You’ve a smart mother re the 3k, very wise use of that)
What is market rent on the rented house
Why do you want to keep it
I would like to pay down the mortgage but had been keeping it to pay the fair deal 80k bill when it happens.


If I use the spare cash to pay most of my mortgage, could I get a small mortgage on the house to pay the 80k - then pay it off with rental income?
Am also concerned about inheritance tax if the house value continues to rise.
you can borrow from the credit union if you need to. For the Fair Deal.
Currently in Fair deal scheme and will owe back about 80k on the home loan portion. House now worth 400k plus. Also cash assets of approx 30k - rented out so this balance is increasing every month.
Won’t the 80k be subtracted from the value on sale. Your mother can gift you 3k too.
 
I mean if the sale value is 400 k, but the estate owes 80 to fair deal, than the inheritance isn’t 400k, it’s 320k.
 
I don't really understand your point.

On the other hand, if the parent dies and leaves a property worth €400K+ and a Fair Deal loan debt of c. €80K then does the estate, rather than beneficiary/beneficiaries, have to repay the latter, and this might force the sale of the property if there isn't additional cash in the estate to cover the loan?
 
I am assuming that if the house is worth 400k + 30k cash assets = 430k, then 80k is payable from the estate. I thought I could raise funds to pay this but not if it has to be paid from the estate I suppose. Will probably need to ask a solicitor that question.
Anyway - I had planned on either using the cash I have to pay the 80k and therefore keep the house or getting a small mortgage to cover this. Would I qualify for a buy to let mortgage at my age? If it needs to be a credit union loan I’d need to keep those savings in the credit union to secure a loan.
Brontë - I will come back with answers to your questions- I’ll check the figures.

Thanks
 
On the house rental - I would hope that my current Ukranian tenants would stay - they have been with me since the war broke out and are really good tenants. However they are paying 1200 per month + 400 per month contribution under the ARP scheme which is due to finish in Feb 2026. This is well below current rental rates so will need to decide what to do - whether to get tenants able to pay the full rate but who know who I would get or stick with existing tenants paying a lower rent.
Keep in mind that if you rent to them at below market, you are stuck with that rent for 6 years plus max 2%. You're highly likely not to get an increase at year 6 either, that will become a political football. You won't be able to sell with vacant possession within the 6 years either and again you may not be able to at year 6 because of yet another change in the rules or an eviction ban.

You should really look at the other threads here on the PRS. Just because the ARP scheme worked well, that is no guarantee that the PRS will be equally good, in fact problems of one type or another seem to be frequent in the PRS.
 
On the other hand, if the parent dies and leaves a property worth €400K+ and a Fair Deal loan debt of c. €80K then does the estate, rather than beneficiary/beneficiaries, have to repay the latter, and this might force the sale of the property if there isn't additional cash in the estate to cover the loan?
The State doesn't care who repays the Fair Deal loan, as long as it's repaid. Yes, it's a liablity of the estate, and if nobody repays it then the State will pursue the executor. But if the estate would need to sell the house in order to raise funds to repay the loan, and the person who stands to inherit the house would rather inherit the house than the net proceeds of sale, there's no problem with that person repaying some or all of the Fair Deal loan so that the estate doesn't have to repay it, and so doesn't have to sell the house in order to repay it.
 
I don't really understand your point.

On the other hand, if the parent dies and leaves a property worth €400K+ and a Fair Deal loan debt of c. €80K then does the estate, rather than beneficiary/beneficiaries, have to repay the latter, and this might force the sale of the property if there isn't additional cash in the estate to cover the loan?
Estate consists of

House 400K
Cash 30K
Fair Deal debt of 80K.
Net estate is 400 + 30 = 430 - 80 = 350. OP will have zero inheritance tax on the inheritance of 350K. Because her threshold is 420K.

Presumably the 30K will grow. 80-30 = 50K. She needs to find 50K. Which she already has. (there will be funeral costs, and probate costs in addition).
 
On the house rental - I would hope that my current Ukranian tenants would stay - they have been with me since the war broke out and are really good tenants. However they are paying 1200 per month + 400 per month contribution under the ARP scheme which is due to finish in Feb 2026. This is well below current rental rates so will need to decide what to do - whether to get tenants able to pay the full rate but who know who I would get or stick with existing tenants paying a lower rent.
I'm not an expert on this. But I did google. (Gov.ie + citizens advice).

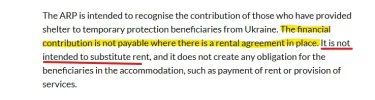
This scheme pays 400 per month. It ends in March. I do not understand how you are also getting 1200 from the Ukranians in addition. I believe you are incorrectly in ARP and incorrectly not registered with the RTB. I refer to this


1793350269569.webp

If this is the case, you should regularise the situation.
 
Last edited:
Back
Top