Age: 53
Spouse’s/Partner's age:48
Annual gross income from employment or profession:
€114,000 + 10,000 Bonus
Annual gross income spouse:
150,000 + 30,000 Bonus
Monthly take-home pay:
€8,500 approx (after pension contributions etc. We have company health insurance and death cover).
Type of employment:
Private sector
Expenditure pattern:
After-school childcare at 450 per month.
Mortgage on rental property is approx 1,250 per month.
Excluding these we probably spend 3-3.5k per month. But prob spend another 7-10k annually on holidays.
Rough estimate of value of home
€950,000
Mortgage on home
None
Other borrowings – car loans/personal loans etc
None
Do you pay off your full credit card balance each month?
Yes
Savings and investments:
Me:
€20k Cash savings.
€50k 10 year state savings bond. (Maturity 2032)
€12k Prize bonds
Wife:
200k cash savings
20k regular savings.
Joint Savings
80k Zurich Prisma 4
12k Zurich Prisma 5 ( just started contributing 4k per month to this)
3k Zurich Prisma 5 (kids investment to max out the 3k per year tax free)
Do you have a pension scheme?
Me €380,000 previous pension (Aviva buyout bond)
Me €360,000 new pension
Wife pension €500,000 (Aon lifestyle type fund)
My company pays 10% and I pay 30% (max for tax relief).
Wife's company pays 10% and she pays max without exceeding the 115,000 cap. .
Do you own any investment or other property?
Yes. Value €500,000. Mortgage tracker ECB+1.15% €130,000 remaining (14 years). Rented for €2250 a month gross. Agency looking after it. Have just giving notice on this in June hoping to put on market march next year assuming tenants vacate.
Ages of children: 2 children - ages 12 and 8.
Life insurance:
Mortgage protection on both properties.
Health insurance thought jobs.
Death in benefit through jobs.
Other info
I have received all my parental inheritance.
My wife has received some inheritance but will likely receive a high 6 figure sum in the next 10 years also.
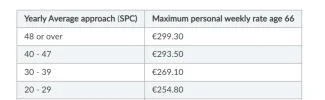
I have approx 1360 contributions towards the state pension.
My wife currently has a similar amount of credits.
What specific question do you have or what issues are of concern to you?
I would like to retire as soon as I comfortably can. Ideally on three years So my PRSI pension contributions would fall short for a full state pension in three years time.
I realise with small kids retirement may be a while away but I'm trying to assess how far away. So any thoughts on that welcome.
My wife would like to continue working until she is 55/57. I would like to be finished in 3 years at 56. I want to spend more time with my kids, I have hobbies that I would like to pursue if time allowed also. I have no interest in moving into a different area of work and going part time is not an option.
Do you think retirement in 3 years is realistic?
Anything else I need to consider or suggestions as to things we should do to plan for retirement.
Any advice on what to do with the lump sum when we sell the rental property next year?