Deferring your State Pension (Contributory) - break even point is age 88

I was wondering if a younger spouse would be able to claim an increase for a qualified adult based on my contributory state pension while deferring her own contributory pension until age 70. She will not have the full 2080 credits even by age 70 so was thinking that she would also add credits during deferral either by taking ARF distributions of 5K or by making voluntary contributions. I think she should be able to meet the associated income criteria based on her income/assets. It so it seems like deferring would be highly beneficial to people in such situations.
 
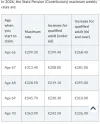
2026 State Pension (Contributory) Rates
Break Even age now at 87/88
Age when you start to claimMaximum rateper yeardiff v 66
Age 66€299.30€15,617.47€0.00
Age 67€313.70€16,368.87€751.39
Age 68€328.90€17,162.00€1,544.53
Age 69€345.70€18,038.63€2,421.15
Age 70€363.90€18,988.30€3,370.83
Age6667686970
66€15,617.47€0.00€0.00€0.00€0.00
67€31,234.95€16,368.87€0.00€0.00€0.00
68€46,852.42€32,737.73€17,162.00€0.00€0.00
69€62,469.90€49,106.60€34,324.00€18,038.63€0.00
70€78,087.37€65,475.46€51,486.01€36,077.25€18,988.30
71€93,704.84€81,844.33€68,648.01€54,115.88€37,976.60
72€109,322.32€98,213.20€85,810.01€72,154.50€56,964.91
73€124,939.79€114,582.06€102,972.01€90,193.13€75,953.21
74€140,557.27€130,950.93€120,134.01€108,231.76€94,941.51
75€156,174.74€147,319.79€137,296.02€126,270.38€113,929.81
76€171,792.21€163,688.66€154,458.02€144,309.01€132,918.11
77€187,409.69€180,057.53€171,620.02€162,347.63€151,906.42
78€203,027.16€196,426.39€188,782.02€180,386.26€170,894.72
79€218,644.64€212,795.26€205,944.02€198,424.89€189,883.02
80€234,262.11€229,164.12€223,106.03€216,463.51€208,871.32
81€249,879.58€245,532.99€240,268.03€234,502.14€227,859.62
82€265,497.06€261,901.86€257,430.03€252,540.76€246,847.93
83€281,114.53€278,270.72€274,592.03€270,579.39€265,836.23
84€296,732.01€294,639.59€291,754.03€288,618.02€284,824.53
85€312,349.48€311,008.45€308,916.04€306,656.64€303,812.83
86€327,966.95€327,377.32€326,078.04€324,695.27€322,801.13
87€343,584.43€343,746.19€343,240.04€342,733.89€341,789.44
88€359,201.90€360,115.05€360,402.04€360,772.52€360,777.74
 
I was wondering if a younger spouse would be able to claim an increase for a qualified adult based on my contributory state pension while deferring her own contributory pension until age 70.
I have been wondering about that also. I suspect that if they don't apply for the COAP @ 66 the qualifying adult increase will just continue.
 
I was wondering if a younger spouse would be able to claim an increase for a qualified adult based on my contributory state pension while deferring her own contributory pension until age 70
That should be possible. Great idea!

It is possible to qualify for benefits after age 66, Jobseekers benefit for example.
 

The rates for deferral at age 69 and 70 are now included


Screenshot_20260130-111634.webp
 
Last edited:
I was wondering if a younger spouse would be able to claim an increase for a qualified adult based on my contributory state pension while deferring her own contributory pension until age 70.
Here it says "If you are getting another social welfare payment during the deferral period, your SPC age rate will be stepped back by the length of time (in weeks) you are on the social welfare payment." . . so if the qualified adult increase is viewed as a welfare payment to the younger spouse then I expect that they wouldn't get an increased rate of pension based on age, though would be able to collect more PRSI during that time.

Methinks the qualified increase probably wouldn't be viewed as a welfare payment to the younger spouse and that it would all probably work out, but it seems trappy.
 
Methinks the qualified increase probably wouldn't be viewed as a welfare payment to the younger spouse and that it would all probably work out, but it seems trappy.
Yes I don't think that it could be considered as a payment to the younger spouse.

The younger spouse is not allowed PAYE tax credits on the payment because under DSP rules the payment is made to the other spouse. This other spouse cannot claim extra PAYE tax credits on the extra payment either, because these are not transferable between the partners.
 
The younger spouse is not allowed PAYE tax credits on the payment because under DSP rules the payment is made to the other spouse

So for future pension planning do i need to treat the IQA as my income even though it is paid directly to my spouse?
 
So for future pension planning do i need to treat the IQA as my income even though it is paid directly to my spouse?
From a taxation and DSP position it is a payment to you.
The increase for a qualified adult will appear in your welfare payments record and in your earnings for PAYE.

The direct payment to your spouse is just a diversion of some of your Pension entitlement to your spouse.

As a couple you could be disadvantaged by this method of making you liable for the taxation of the increased payment.

If your spouse was liable for taxation they could make use of their own PAYE tax credits to possibly reduce or fully eliminate any tax on the increased payment.
 

Just 220 people opt to defer state pension despite higher weekly payments on offer​

Just 220 people have so far taken advantage of Ireland’s deferred state pension scheme, opting to postpone drawing it down for a year or two.

Newly released figures show that 194 people chose to take their pension at 67, instead of the usual age of 66.

A further 26 people waited until they were aged 68, according to data from the Department of Social Protection.
...
The department said there were a further 365 cases where customers had indicated they wanted to postpone their pension. However, they had not provided information on when they planned to do this.
 
Back
Top