Savvy Sally
Registered User
- Messages
- 10
Hello all,
I previously asked this community for a view on setting up a PRSA and carrying tax relief forward as I do not currently have earned income. As mentioned I am in the fortunate position to have a lump sum that I can invest for the next 15 years. After careful consideration of my overall circumstances, taking the views of this community into account which I am very grateful for, the fact that I need pension diversification and flexibility on drawdown timing I have decided to go ahead with setting up this PRSA.
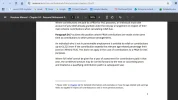
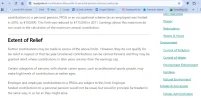
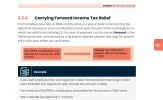
I have contacted a number of life assurance companies and brokers to discuss setting up this PRSA. The brokers I have spoken to were not supportive of the idea. One life assurance company, direct sales team, has a compelling offering of an execution-only PRSA with low annual management fees and access to a broad range of passive index funds which suits my needs. However, said life assurance company has come back to me stating that “Under Irish tax rules, you cannot carry forward (roll forward) unused PRSA tax relief to future years”. This statement is contrary to my understanding of tax and pension rules based on a the following (attached for reference):
Does anyone in this community have experience of carrying unrelieved contributions to PRSA forward to future years? Are there any other citations or references that you would include to support the argument that relief can indeed be carried forward?
All thoughts and guidance welcome.
With many thanks in advance.
I previously asked this community for a view on setting up a PRSA and carrying tax relief forward as I do not currently have earned income. As mentioned I am in the fortunate position to have a lump sum that I can invest for the next 15 years. After careful consideration of my overall circumstances, taking the views of this community into account which I am very grateful for, the fact that I need pension diversification and flexibility on drawdown timing I have decided to go ahead with setting up this PRSA.
I have contacted a number of life assurance companies and brokers to discuss setting up this PRSA. The brokers I have spoken to were not supportive of the idea. One life assurance company, direct sales team, has a compelling offering of an execution-only PRSA with low annual management fees and access to a broad range of passive index funds which suits my needs. However, said life assurance company has come back to me stating that “Under Irish tax rules, you cannot carry forward (roll forward) unused PRSA tax relief to future years”. This statement is contrary to my understanding of tax and pension rules based on a the following (attached for reference):
- Chapter 24 in the Pensions Manual (see the bottom of page 5 specifically) states that relief can be carried forward
- The Irish Legal Guide also states that “unrelieved contributions can be carried forward….”
- The current Institute of Bankers (IOB) pension education materials state that you can carry relief forward on unrelieved contributions to PRSAs
Does anyone in this community have experience of carrying unrelieved contributions to PRSA forward to future years? Are there any other citations or references that you would include to support the argument that relief can indeed be carried forward?
All thoughts and guidance welcome.
With many thanks in advance.