VulpusVulpus
Registered User
- Messages
- 36
Personal details
Your age: 60
Your spouse's age: 60
Number and age of children: 2, adults, in later stages of full-time education
Income and expenditure
Annual gross income from employment or profession: zero
Annual gross income of spouse/partner: varies since largely self-employed. Regular monthly net income in region of 30-40k/year but has a lucrative second income stream which can total 100k or more in a year.
Monthly take-home pay: zero from employment
Rental income: 10K in Ireland, 14K elsewhere in EU. This is net after expenses and taxes.
Type of employment - Early retirement from private sector a few years ago
In general are you:
(a) spending more than you earn, or
(b) saving?
Summary of Assets and Liabilities
Family home value: total estimated value 325K of which I own half. My wife owns the other half.
Mortgage on family home: zero
Net equity: 162K
Other property in family and personal use: city apartment and summer house, total value 450k (100% owned by me)
Cash: 40k, however much of this is currently in USD which is a risk point, although it gets 4% interest. So right now am quite low on EUR cash.
Defined Contribution pension fund: total 675k value across 3 funds, see Pension Information below.
Other investment fund: 180K (invested in Dimensional 80/20 EUR-hedged fund)
Company shares: 10k in Ryanair stock
Other: 42k (50K USD) in an S&P 500 tracker ETF
Buy to Let Property value:
Total net assets: adding up the above.
1) Property in personal and family use: 612K Eur
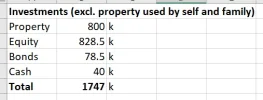
2) All other assets: 1,747K Eur
Other borrowings – car loans/personal loans etc
No borrowings
Pension information
Value of pension funds 1 and 2 (Ireland-based occupational pension schemes): Total 250k as of December 2025.
Value of pension fund 3: 425K as of May 2025 (waiting on up-to-date annual statement so I don't have a current valuation), Malta-based.
The first 2 funds are invested in medium-higher risk global equity funds, they have generally good historical performance. I get regular reminders to "lifestyle" them which I ignore. I considered changing them to ARFs but decided not to do it at the moment since I have no near-term need to draw them down.
The third fund is a managed fund invested 90% Global Equities, 10% Bonds.
Note than I am tax-resident in an EU country where tax is not levied on growth in pension funds, so there should be no CGT due when I draw these down.
Buy to let properties
Already listed above but I repeat it here.
Value: Total 800K (450K in Ireland, 350K elsewhere in EU)
Rental income per year: Net after expenses and taxes 24K (10K in Ireland, 14K from EU properties)
No mortgages.
Other savings and investments:
Listed above
Other information which might be relevant
I am tax-resident in another EU country but visit Ireland frequently. I have considered retirement to Ireland but probably will not do that, the roots are too deep abroad by now. My property in Ireland would be useful for me in future to spend periods in Ireland, if I exit being a landlord.
My eventual state pension will be about 50% from Ireland, 50% from where I live now. The latter will most likely be less than Ireland since current pension levels probably around 50-60% of Ireland.
What specific question do you have or what issues are of concern to you?
I feel quite financially secure, early retirement was a good decision, and I just want to make sure I manage my money to see me through my life, help my children get established post-university, and although my wife is currently self-supporting I want to make sure she also has enough if I die young and she would cease working.
In a few weeks I will have an annual review with my financial advisor of many years and I welcome any feedback or ideas from this forum to bring to that discussion. We update a forecasting model which always shows my total asset values will remain fairly stable over the next couple of decades. The FA usually tells me to increase my cash holding and consider putting more into bonds as an insurance as my exposure to the stock market is a too high with respect to having ready-cash for next 1-2 years. I know I am currently much too low on cash and need to fix that.
Your age: 60
Your spouse's age: 60
Number and age of children: 2, adults, in later stages of full-time education
Income and expenditure
Annual gross income from employment or profession: zero
Annual gross income of spouse/partner: varies since largely self-employed. Regular monthly net income in region of 30-40k/year but has a lucrative second income stream which can total 100k or more in a year.
Monthly take-home pay: zero from employment
Rental income: 10K in Ireland, 14K elsewhere in EU. This is net after expenses and taxes.
Type of employment - Early retirement from private sector a few years ago
In general are you:
(a) spending more than you earn, or
(b) saving?
- I am living off my savings and investments, and rental income.
- I plan with 90k/year including children's university costs but I don't track very carefully my expenditure.
- Probably my personal expenditure is higher than I estimate but I know the kid's costs are a good bit less than my "worst case" budget for them.
- I don't have any major extravagances like yachts or expensive cars. I take 1-2 holidays abroad a year.
Summary of Assets and Liabilities
Family home value: total estimated value 325K of which I own half. My wife owns the other half.
Mortgage on family home: zero
Net equity: 162K
Other property in family and personal use: city apartment and summer house, total value 450k (100% owned by me)
Cash: 40k, however much of this is currently in USD which is a risk point, although it gets 4% interest. So right now am quite low on EUR cash.
Defined Contribution pension fund: total 675k value across 3 funds, see Pension Information below.
Other investment fund: 180K (invested in Dimensional 80/20 EUR-hedged fund)
Company shares: 10k in Ryanair stock
Other: 42k (50K USD) in an S&P 500 tracker ETF
Buy to Let Property value:
- Investment property in Ireland, value 450k. I don't wish to sell but it's a part-4 tenancy which I may exit when it comes up for renewal, as I see too many risks to continue as a landlord.
- 3 investment properties elsewhere in EU, value 350K, currently rented out. All 3 apartments are in desirable city locations and can be easily sold if necessary, subject to notice to tenants (no restrictions like in Ireland).
Total net assets: adding up the above.
1) Property in personal and family use: 612K Eur
2) All other assets: 1,747K Eur
Other borrowings – car loans/personal loans etc
No borrowings
Pension information
Value of pension funds 1 and 2 (Ireland-based occupational pension schemes): Total 250k as of December 2025.
Value of pension fund 3: 425K as of May 2025 (waiting on up-to-date annual statement so I don't have a current valuation), Malta-based.
The first 2 funds are invested in medium-higher risk global equity funds, they have generally good historical performance. I get regular reminders to "lifestyle" them which I ignore. I considered changing them to ARFs but decided not to do it at the moment since I have no near-term need to draw them down.
The third fund is a managed fund invested 90% Global Equities, 10% Bonds.
Note than I am tax-resident in an EU country where tax is not levied on growth in pension funds, so there should be no CGT due when I draw these down.
Buy to let properties
Already listed above but I repeat it here.
Value: Total 800K (450K in Ireland, 350K elsewhere in EU)
Rental income per year: Net after expenses and taxes 24K (10K in Ireland, 14K from EU properties)
No mortgages.
Other savings and investments:
Listed above
Other information which might be relevant
I am tax-resident in another EU country but visit Ireland frequently. I have considered retirement to Ireland but probably will not do that, the roots are too deep abroad by now. My property in Ireland would be useful for me in future to spend periods in Ireland, if I exit being a landlord.
My eventual state pension will be about 50% from Ireland, 50% from where I live now. The latter will most likely be less than Ireland since current pension levels probably around 50-60% of Ireland.
What specific question do you have or what issues are of concern to you?
I feel quite financially secure, early retirement was a good decision, and I just want to make sure I manage my money to see me through my life, help my children get established post-university, and although my wife is currently self-supporting I want to make sure she also has enough if I die young and she would cease working.
In a few weeks I will have an annual review with my financial advisor of many years and I welcome any feedback or ideas from this forum to bring to that discussion. We update a forecasting model which always shows my total asset values will remain fairly stable over the next couple of decades. The FA usually tells me to increase my cash holding and consider putting more into bonds as an insurance as my exposure to the stock market is a too high with respect to having ready-cash for next 1-2 years. I know I am currently much too low on cash and need to fix that.
Last edited: