Moneymakeover 44 year old teacher with cash on deposit

Riggsby

New Member
Messages
5
Age:
44
Spouse’s/Partner's age:
47

Annual gross income from employment or profession:
€78,832 (acting up the last two years , €91,749)
Annual gross income spouse:
€79,543

Type of employment:
Both teachers

Expenditure pattern:
We are both generally 'savers'

Rough estimate of value of home
€750,000
Mortgage on home
paid off

Other borrowings – car loans/personal loans etc
None

Do you pay off your full credit card balance each month?
Yes

Savings and investments:
€150,000 in savings split between two Bunq savings accounts
€300 a month going into a 20 year Zurich foursight saving account. currently €23,000. Matures 2041
€500 a month going into Comhar Linn credit union

Do you have a pension scheme?
Yes, both of us are post April 2004. New Entrants 1
Both of us used Cornmarket in the past to setup AVC via Irish Life. Both are contributing 15%.

We could contribute 25% due to our age.

Do you own any investment or other property?
No.

Ages of children:
None.

Life insurance:
Not since mortgage paid off. Illness insurance with Zurich.

What specific question do you have or what issues are of concern to you?
If we want to retire early. In the next 10 to 13 years what would be the best use of the money in Bunq. Which is being eaten by inflation. The interest rate resets every six months so we only earn 1.51% on most of it and 3.01% on anything over the amount that was in it in Jan and July.

I'm looking for broad advice on what to do with the cash.

Go to an independent financial advisor? (we realised too late that Cornmarket is expensive and deals only with specific companies).

Put it in a few fixed term accounts in Raisin?

Do it all ourselves?

Thank you all very much for taking the time to read this.
 
Last edited:
€300 a month going into a 20 year Zurich foursight saving account. currently €23,000. Matures 2041
What exactly is this and how is the money invested?
If it's not in equities for a 20 year term then it's likely a poor choice.
I'm looking for broad advice on what to do with the cash.
How and when are you likely to use the cash?

With presumably secure teaching jobs and guaranteed pensions you can almost certainly afford to take on more risk/volatility with medium/long term savings than just sticking it on deposit for, at best, marginal after tax/inflation returns.
Both are contributing 15%.

We could contribute 25% due to our age.
Unless there is some risk of over funding your pensions (I don't really understand public service/teachers' pensions, sorry) then it seems like a no brainer to me to maximise your AVCs. Also make sure that the charges are competitive and the asset allocation is appropriate - most likely all equities for your ages and situation.
 
Last edited:
Hi Clubman,
Thank you for the reply.
The Zurich savings is called Balanced Pensions and Investments. It is set to auto fund switch based on my chosen investment strategy (adventurous)
Which is just me regurgitating Zurich speech. I am conscious of the fact that there is 15 years left on it. Might it be a good idea to encash now and use it with the bunq money?

With the remaining cash we are hoping to use it in either retire in 10 or 13 years. If 13 years spouse will be 60 and her AVC will be sufficient to retire. I would like to be able to retire at the same time, so would need a mix of AVC and this cash.

However If the cash was able to allow both of us to retire in 10 years instead that would be great.

You are right about the 25%. I'll redo our budget and make it work.
 
The Zurich savings is called Balanced Pensions and Investments. It is set to auto fund switch based on my chosen investment strategy (adventurous)
Which is just me regurgitating Zurich speech. I am conscious of the fact that there is 15 years left on it. Might it be a good idea to encash now and use it with the bunq money?
I don't understand this. Is it a pension or a non-pension savings/investment plan? What is it invested in? What charges apply?
With the remaining cash we are hoping to use it in either retire in 10 or 13 years. If 13 years spouse will be 60 and her AVC will be sufficient to retire. I would like to be able to retire at the same time, so would need a mix of AVC and this cash.
In that case, apart from keeping a modest emergency fund for contingencies (unlikely to include either or both of you losing your jobs) you might be better off maximising your AVCs and investing most or all of the rest in something like a diversified, low charges, passive index tracker via a fund or ETF etc.

I'm assuming that you won't need significant funds for stuff like upgrading your home etc. in the meantime?

You also shouldn't forget to spend a bit and live a little while you're young and without dependents.
 
However If the cash was able to allow both of us to retire in 10 years instead that would be great.
You might look into using it to fund AVC contributions (on the assumption you can take benefits early from your teacher pensions).
 
I don't understand this. Is it a pension or a non-pension savings/investment plan? What is it invested in? What charges apply?
It's an investment plan. Pension funds and life assurance funds are exactly the same as they are both gross roll up. Zurich are just including this in the name of the fund.
 
Are you hoping to take CNER or a preserved pension at your normal retirement age? This could also influence whether you go for AVCs (whichyou can only draw down at the same time as your pension) or a separate investment fund to tide you over until drawing down your preserved pension
 
Sorry all. new accounts have an hour delay before I can post again.
all of the rest in something like a diversified, low charges, passive index tracker via a fund or ETF etc.
Thank you. Will start looking into this.
You might look into using it to fund AVC contributions
Thanks. will see if its possible,
Are you hoping to take CNER or a preserved pension at your normal retirement age?
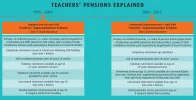
Typically, public servants hired after 1st April 2004 can't retire early, other than taking CNER.
Thank you for this. I was planning on CNER. I had been told that I could draw down the AVC to bring the DES lump sum, 1.5 × final salary, up to where it should be and put the rest in a retirement fund.
What is the allocation rate and AMC on your AVCs from Cornmarket / Irish Life?
The AMC is 1.5% and the allocation rate is 100%

Is there a group Income Protection scheme for teachers?
Yes, INTO Salary Protection Scheme with Irish Life.
 
Both of us used Cornmarket in the past to setup AVC via Irish Life. Both are contributing 15%.

You are contributing over 15,000 a year to two AVCs, and paying 1.5% AMC.

That is a high charge. Personally, I would not pay it. Bear in mind that the AMC dominates all other charges in the long-run.

I suggest moving to a lower-cost AVC.

For example, see here:

 
You are contributing over 15,000 a year to two AVCs, and paying 1.5% AMC.
Sorry I mistyped. the AMC is 1.14% Still way more than the .55% you have there from Royal London. Right now I'm basically paying more for convenience, ie payroll deduction. I'll investigate how transferring would work.
Are you absolutely sure that there are no other charges? I seem to recall Cornmarket sometimes charging more for AVCs.

There was an initial fee. I can't remember how big it was but it was paid off over the first year. If there are others, and I'm not saying there aren't, I can't find them in my statements.
 
Sorry I mistyped. the AMC is 1.14% Still way more than the .55% you have there from Royal London. Right now I'm basically paying more for convenience, ie payroll deduction. I'll investigate how transferring would work.


Funds above 40,000 are subject to 1.14% - 0.25% = 0.89% AMC.

Funds above 140,000 are subject to 1.145 - 0.50% = 0.64% AMC
 
You probably are paying 1.5% AMC on the first 40k in your AVC fund.

You should both switch to someone like Royal London Ireland and get a better AMC. Just stop paying in to those corn market/Irish Life AVC funds and start new ones with a better value provider. The difference will be thousands more in your AVC pots by retirement.

Once a year you will need to do your tax return on revenue.ie to get the tax relief, it's not hard.

Other posters on here have said you can get the tax relief yourself with each regular contribution. I could never figure that out. If you don't want, or can't afford, to wait and get the tax relief paid back to you as a lump sum once a year then maybe you should stay with Cornmarket.

I have written to FORSA union to complain that public sector employees have essentially no choice if they want tax relief at source from AVCs deducted from payroll by their employer.

I would like to know how complicated it would be for public sector payroll offices to facilitate tax relief at source on AVCs made to multiple types of pension providers. How much extra work would that be for payroll? Surely it wouldn't have to be more complicated, than only facilitating Cornmarket, once the electronic systems are set up properly.
 
1.14% is not very high, but I still would not pay it, especially if the fund is large, and will continue to gro
You probably are paying 1.5% AMC on the first 40k in your AVC fund.
Thank you both. You've convinced me to talk to Royal London.
You're right it's really pretty unfair that Cornmarket are our only options for deduction at source.
I really appreciate all of your help today.
Thanks again
 
Back
Top