401K tax, is it included in the 200K tax free lump sum in Ireland?

homeowner

Registered User
Messages
184
When I turn 59.5 I will be able to access a small 401K in the US from when I worked there in the 1990s. Its about €45K. I believe I will have to pay 30% tax in the US on the withdrawal of the full amount, lets say that is about €15K.
1. Does the 45K count towards the tax free lump sum in Ireland of 200K considering it will not be tax free, and is it 30K that is counted against the 200K or the whole 45K?
2. is there anyway to offset the 15K US tax against irish income tax in that same year if I am still working
3. Is there any scenario in the irish tax system that gets me a credit of the 15K US tax or an offset, if I am not working at 59.5
 
Have you had a chance to read Revenue's documentation(quite short):

and

Also from LIA goes in to this a bit more:

No direct experience so avoided given my thoughts on this.
 
Yes I have read both of those and some other sources but I am still not clear of exactly what/when is the most efficient way to bring back this lump sum so as to incur the least amount of tax and impact to future tax free lump sums.
 
Hello, I am in a similar position and I'm currently navigating the endless contradictions of information about tax implications. I live in Ireland, returning from the US over 20 years ago. I recently withdrew the full value of my 401K (a similar sum to yours) and have done so before I reach 59.5. However, I submitted a Form W8 Ben (not sure if you have done this?) to the fund administrators which meant I was not obliged to pay US taxes under the double taxation treaty agreement between Ireland and the US. My next step is to confirm whether or not the 401k can be considered part of the lifetime 200K tax free lump sum or if it is to be considered as income and means I am liable for PAYE and USC. The articles above confused me even further. Don't waste your time contacting the National Pensions Helpline (they are a ghost) - I have made at least 6 submissions to them with zero response - they don't take calls, they don't respond to emails and at submitting queries via their website have proved fruitless. I'd be interested to hear how you get on; I'll try to add an update as I go.
 
@homeowner @CorkBoston1994

I wouldn't spend too much time tying yourself in knots - its a painfully circular area where revenues vague guidance interact with the US-IRL DTA and vice versa.......speak to Stephanie Wickham or team member at ExpatTaxes (www.expattaxes.ie) - a single call will put this to bed in a way that is rooted in law and recent case studies. The consultation is on the face of it expensive but no reason why you both couldn't team up to get all your questions answered with one call.

The other idea I would consider is that in the US there is a concept of void due to vagueness - which says your due process rights are violated if a law is so unclear that a reasonable person cannot understand their obligations under it. Now I'm not saying you skip paying tax but what I am saying is when one is presented with a wall of gobbledygook by their Government's taxing authority I'd argue the obligation shifts back to the tax authority to 'correct' YOUR assessment of THEIR gobbledygook.

So when revenue cant be bothered to write some plain English guidance for the five countries where 95% of the Irish diaspora end up working during their career (USA, Canada, UK, Australia, EU) then I'm not sure how much time or bother one should spend getting to the second decimal place of their euro obligation.

So in the round speak to ExpatTaxes, get the broad principles & mechanics of reporting and file whatever taxes are due based on your understanding and essentially push the obligation back to revenue to disagree.
 
Last edited:
Don't waste your time contacting the National Pensions Helpline (they are a ghost)
As @Fortune says, they aren't an official body even if their site seems designed to mislead people into thinking that they are.
 
@letitroll
Cheers for that - I fully intend to approach my dealings with Revenue as you prescribe. Unfortunately, I also feel that can work only if you have deep enough pockets that you can employ a consultant to ack on your behalf and a strong enough constitution to go back and forth. Their attitude toward the 'ordinary' taxpayer leaves a lot to be desired.
 
@november16 @Fortune
Thank you, I have considered logging a complaint with Central Bank or the Regulator - I wouldn't mind but I receive a constant flow of marketing emails from them; just no response to my own attempts to contact them.
 
Thank you, I have considered logging a complaint with Central Bank or the Regulator - I wouldn't mind but I receive a constant flow of marketing emails from them; just no response to my own attempts to contact them.
You mean National Pensions Helpline? I never heard anything back on foot of this several years ago...
I've contacted the Pensions Authority about the National Pensions Helpline site and will post back if/when I hear anything back from them
 
Cheers for that - I fully intend to approach my dealings with Revenue as you prescribe. Unfortunately, I also feel that can work only if you have deep enough pockets that you can employ a consultant to ack on your behalf and a strong enough constitution to go back and forth

What I'm suggesting isn't a back and forth quite the opposite. Back and forth will tie you and them in knots. You shouldn't be having any "dealings" with revenue. The only dealing is if/when they come back to query the basis on which you came up with your figures.

Do a consult with ExpatTaxes...do a consult with Gemini......get the basic outline of your opinion of your obligation. Write the math and rational down for YOURSELF only.

on Form12 or wherever input your assessment of the net € income generated from the 401k only (after your assessment of DTA tax credit or whatever).

Submit and pay tax due.

Its revenues job to query or question the basis of your assessment. They most likely wont mainly because of the complexity but also because a taxpayer who without much effort could have likely hidden that foreign sourced pension offshore decided to be honest and pay.
 
I submitted a Form W8 Ben (not sure if you have done this?) to the fund administrators which meant I was not obliged to pay US taxes under the double taxation treaty agreement between Ireland and the US.
Did you get confirmation from the fund administrators that you would not be liable to any US tax on withdrawal? My wife is trying to repatriate her 401k, has submitted the W8BEN but is still being told that she's liable for 30% withholding.

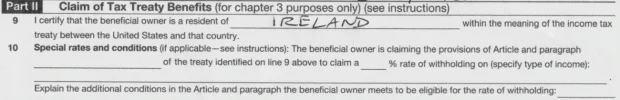
Can I ask a specific question on the W8BEN: what did you enter on Q10 under Part II Claim of Tax Treaty Benefits?

We have received advice that we will not be liable to any Irish tax when we repatriate the funds.

Many thanks!

Screenshot 2026-03-29 21.05.09.webp
 
@letitroll is providing poor / high risk advice in the context of Irish tax obligations. There's no such concept as void to vagueness here.

It's up to a taxpayer to file a return they believe to be correct, in accordance with to the applicable legislation. If you are in genuine doubt about the treatment of any item in your return (or your interpretation of a particular provision relevant to your return) you can complete an expression of doubt. If it turns out your interpretation was incorrect, but your EOD is accepted as valid/genuine, you will be protected from interest and penalties. Otherwise, if you file an incorrect return, you are exposed to being liable to both interest and penalties.

 
Apologies for not getting back to some of these questions sooner - I have messaged one or two of you but just to be clear - once I filed the W8Ben form with the investment broker, I received a cheque for the full value of my 401k fund. The Double Taxation Treaty 1997 is the reference treaty for my W8Ben form.
 
Back
Top